Financing Certificate: What It Is and How It Works
Financing Certificates: What They Are and How They Work
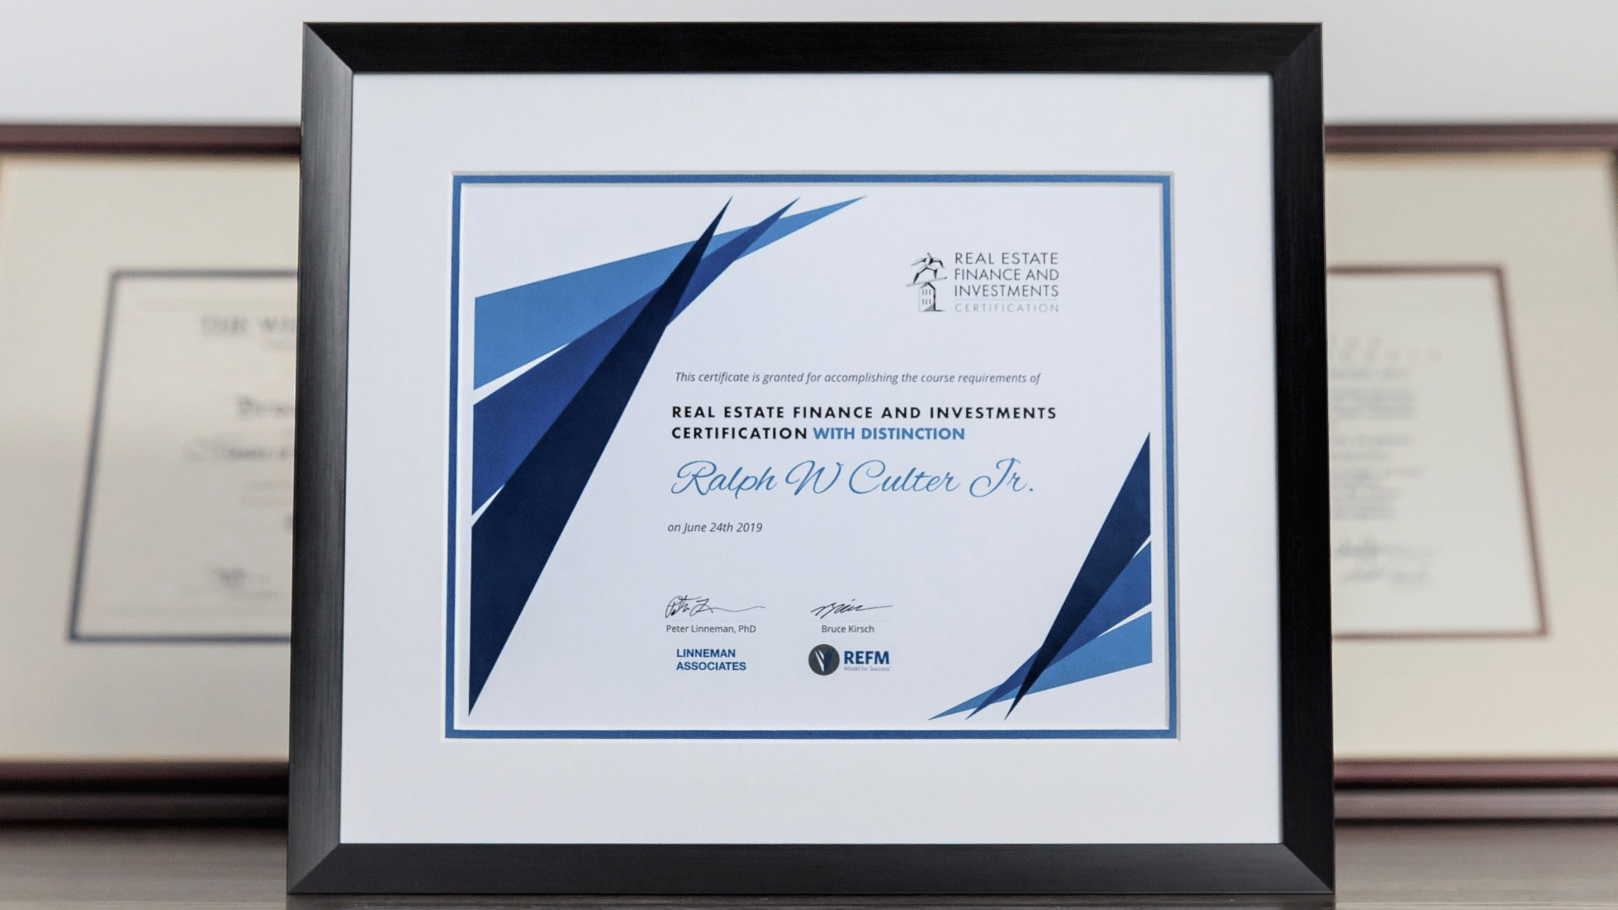
A financing certificate is a document that describes or confirms financing for a purchase. In an auto transaction, it may show that a lender has approved a buyer for a loan, outline the proposed terms, or verify that financing has been arranged. The exact meaning and legal effect can vary by lender, dealership, transaction, and state.
What Information May a Financing Certificate Include?
Depending on how it is used, a financing certificate may list:
- The buyer’s name and identifying information
- The lender or financing provider
- The amount being financed
- The proposed interest rate and repayment term
- Estimated monthly payments
- Any down payment or other conditions
- An expiration date or deadline for completing the transaction
Some certificates reflect a preliminary offer, while others may document a more complete approval. Buyers and dealers should review the document itself rather than assume that every financing certificate guarantees a loan.
How It Fits Into an Auto Purchase
A buyer may seek financing directly from a bank or credit union, arrange financing through a dealership, or compare offers from multiple sources. A certificate or similar approval document can help clarify the financing available for a vehicle. It may also help the parties understand the proposed loan amount and terms before completing the sale.
Final financing can still depend on conditions such as verification of the buyer’s information, the vehicle’s eligibility, lender requirements, and completion of the required paperwork. A preliminary certificate should not be treated as a final loan contract unless the lender’s documentation clearly says that it is.
What Buyers Should Check
Before relying on a financing certificate, buyers should confirm:
- Whether the financing is conditional or final
- How long the offer remains valid
- The annual percentage rate (APR), not just the monthly payment
- The loan term, total amount financed, and total repayment amount
- Any fees, required products, or other conditions
- Whether the terms can change before the loan is finalized
Comparing the APR, loan term, and total cost can provide a clearer picture than focusing on the monthly payment alone. Buyers should keep copies of the certificate, any lender disclosures, and the final signed contract.
What Dealers Should Keep in Mind
Dealers should explain the role of a financing certificate accurately and avoid describing a conditional offer as a guaranteed approval. The certificate should be reviewed alongside the lender’s instructions and the transaction documents. Clear communication helps customers understand what has been approved, what remains outstanding, and when the final financing terms will be confirmed.
Dealers should also follow applicable federal and New York requirements for advertising, credit applications, disclosures, privacy, and vehicle sales. Because requirements can depend on the details of a transaction, consult qualified legal or compliance professionals when questions arise.
A Useful Document, Not Always the Final Word
A financing certificate can make an auto purchase easier to plan by putting proposed financing information in writing. Its value depends on what it confirms and whether any conditions remain. Reviewing the document carefully—and confirming the final terms before signing—helps buyers and dealers avoid confusion and move forward with a clearer understanding of the financing.
5 Key Benefits of a Financing Certificate for Informed and Efficient Purchase Decisions
- Clarifies proposed loan terms
- Helps buyers plan a budget
- Supports faster purchase decisions
- Makes financing offers easier to compare
- Documents approval details and conditions
6 Drawbacks of Financing Certificates: What You Need to Know
- May not guarantee final loan approval.
- Can include conditions or restrictions.
- May expire before the purchase is complete.
- Terms may change after verification.
- Can make buyers focus on monthly payments over total cost.
- May be confusing without clear explanations.
Clarifies proposed loan terms
A financing certificate can clarify the proposed loan terms by putting key details—such as the estimated interest rate, loan amount, repayment period, and monthly payment—in writing. This gives buyers a clearer basis for reviewing the offer, comparing financing options, and asking questions before moving forward. Because the terms may still be conditional or subject to change, buyers should confirm the final details with the lender before signing.
Helps buyers plan a budget
A financing certificate helps buyers plan a budget by outlining key loan details, such as the estimated amount financed, interest rate, repayment term, and monthly payment. With a clearer picture of the expected costs, buyers can compare vehicles and financing options, consider how a car payment fits into their monthly expenses, and make a more informed purchase decision. Actual terms may change if the certificate is conditional, so buyers should confirm the final loan details before signing.
Supports faster purchase decisions
A financing certificate can support faster purchase decisions by giving buyers a clearer picture of their potential budget before they choose a vehicle. With key financing details available in advance, they can compare options, focus on vehicles within their price range, and move through the purchase process with fewer delays—while remembering that final approval and terms may still depend on lender requirements.
Makes financing offers easier to compare
A financing certificate can make financing offers easier to compare by laying out key details—such as the interest rate, loan term, estimated monthly payment, and amount financed—in one place. Reviewing these terms side by side helps buyers look beyond the monthly payment, understand the overall cost of each option, and choose financing that better fits their budget and needs.
Documents approval details and conditions
A financing certificate documents the approval details and any conditions attached to the financing, helping buyers understand what has been approved and what steps remain before the loan is finalized. By putting key terms and requirements in writing, it can reduce confusion and give both the buyer and the dealer a clear reference during the purchase process.
May not guarantee final loan approval.
A financing certificate may not guarantee final loan approval. It can reflect a preliminary or conditional offer, and the lender may still need to verify the applicant’s information, review the vehicle, or confirm other requirements. Until the lender finalizes the loan and provides the definitive terms, financing could change or be declined.
Can include conditions or restrictions.
A financing certificate may include conditions or restrictions that limit how it can be used. Approval might depend on verifying the applicant’s information, choosing an eligible vehicle, meeting a deadline, or satisfying other lender requirements. As a result, the terms shown on the certificate may change—or financing may not be finalized—if those conditions are not met. Buyers should read the document carefully and confirm any requirements with the lender before relying on it.
May expire before the purchase is complete.
A financing certificate may expire before the purchase is complete, especially if the buyer needs more time to choose a vehicle or finish the required paperwork. Once it expires, the lender may require a new application or updated financial information, and the original rate or terms may no longer be available. Buyers should check the expiration date and confirm with the lender whether an extension is possible.
Terms may change after verification.
One drawback of a financing certificate is that its terms may change after the lender verifies the buyer’s information and the vehicle details. The final interest rate, loan amount, repayment period, or monthly payment could differ from the initial estimate, so buyers should review the completed loan agreement carefully before signing.
Can make buyers focus on monthly payments over total cost.
A financing certificate can make it easier for buyers to focus on the monthly payment instead of the total cost of the loan. A payment that seems affordable may result from a longer loan term, which can increase the total interest paid and the amount repaid over time. Buyers should compare the APR, loan term, fees, and total repayment amount—not just the monthly payment—before agreeing to financing.
May be confusing without clear explanations.
A financing certificate can be confusing if its terms and conditions aren’t clearly explained. Buyers may mistake a preliminary approval for a guaranteed loan or misunderstand details such as the interest rate, repayment term, fees, or expiration date. Clear explanations from the lender or dealer can help buyers understand what the certificate confirms, what conditions still apply, and what steps are needed to finalize financing.
Related Post
Empowering Consumers: The Vital Role of an Auto Advocate in Today’s Automotive Industry
The Role of an Auto Advocate in Today’s Automotive Industry The Role of an Auto [...]
Mastering the Art of Effective Advertising Strategies
The Power of Advertising The Power of Advertising Advertising plays a crucial role in today’s [...]